
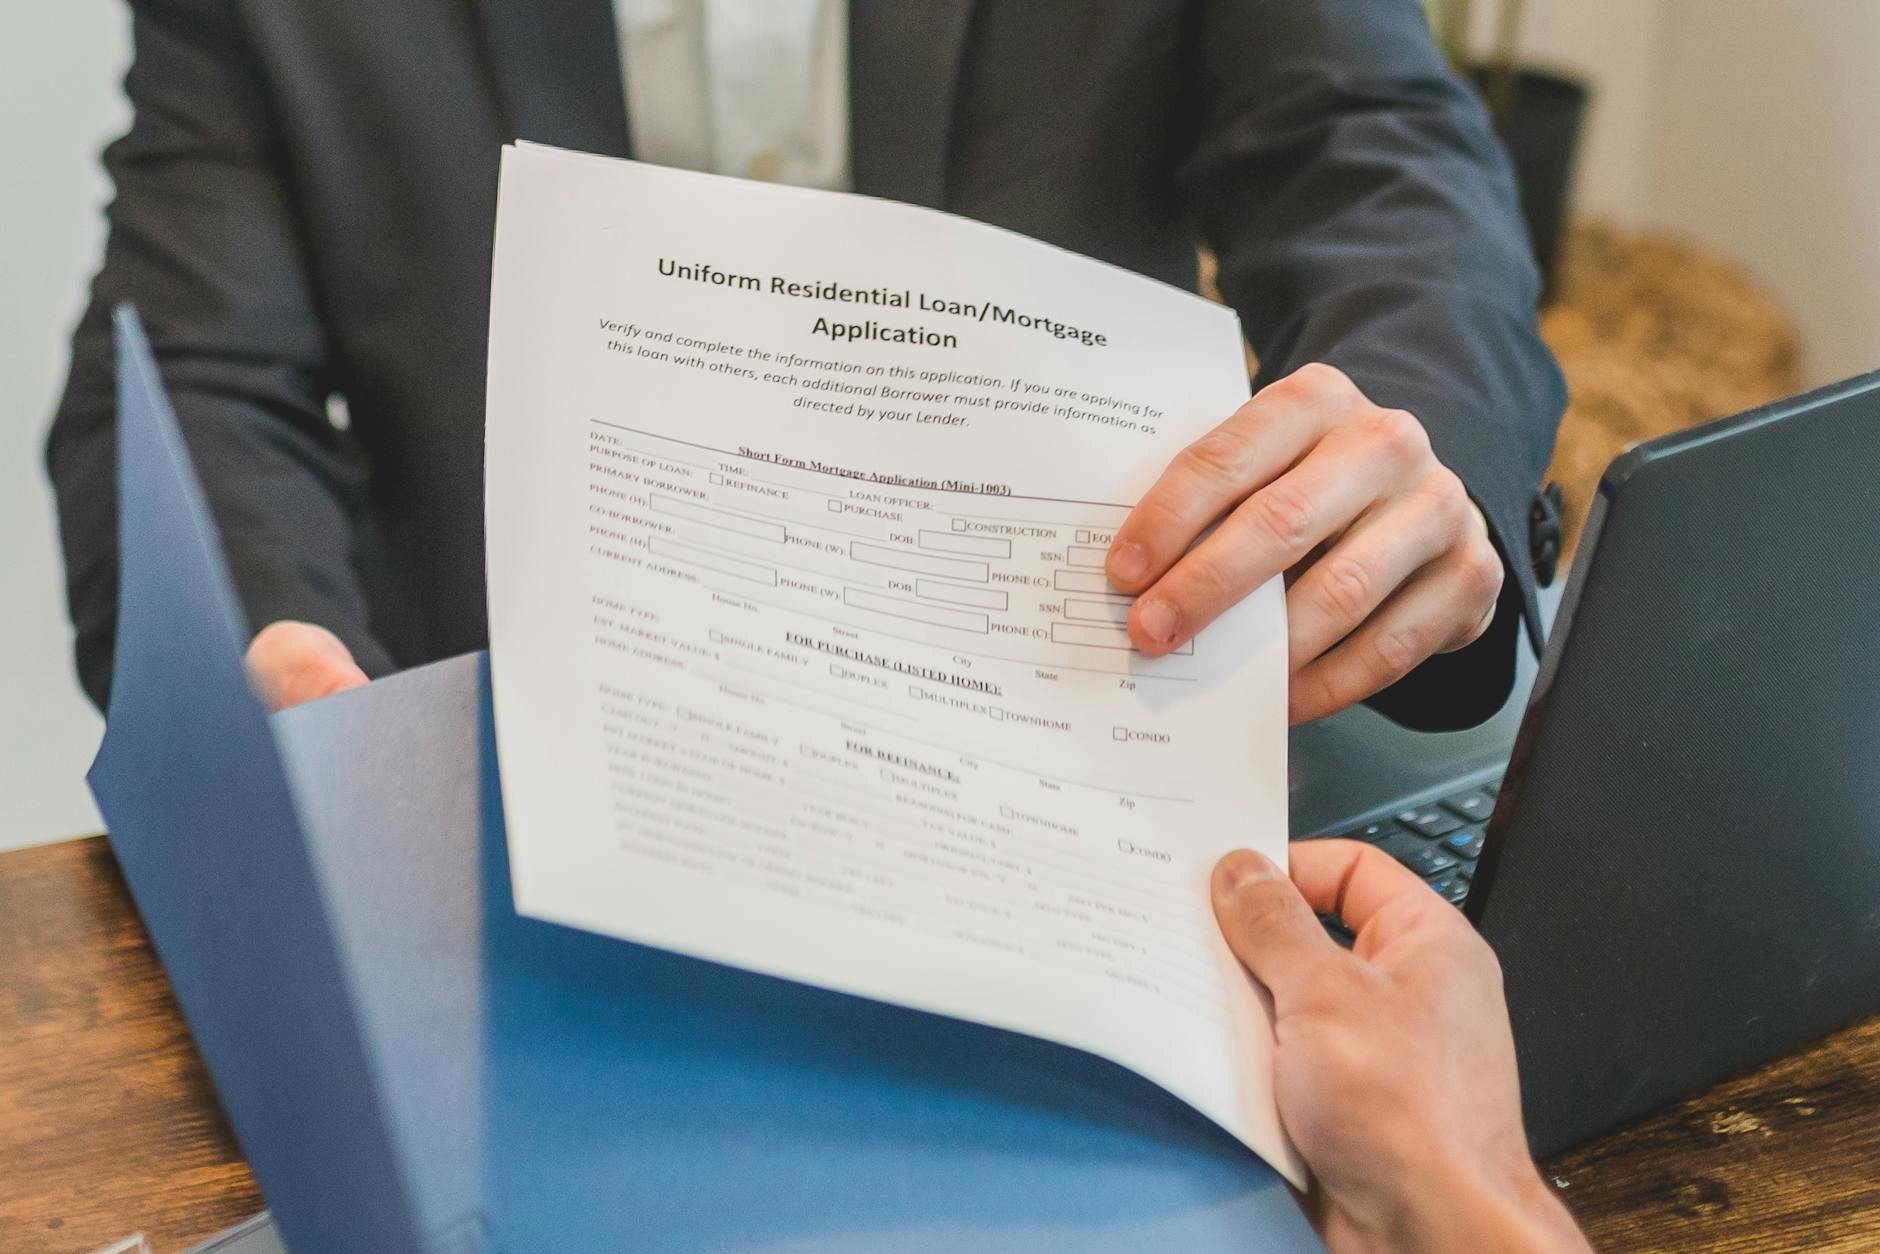
CLEP exam scores can help you earn college credits fast, but FAFSA does not pay for the exam itself. That matters because those credits can still change your enrollment status, your degree progress, and the aid money you keep.
If you plan to test, you need to know how your school counts those credits before you sit for a 90-minute exam. CLEP uses a 20-80 score scale, and 50 is the standard passing score for most exams. That pass mark matters because one score can move you out of remedial classes, shorten your path by a semester, or bump you over a full-time credit line. Schools handle those credits differently, so the same score can help one student and complicate another student's award package. The real trap is not the exam. It is the paperwork after the exam. A student with 9 credits from CLEP may still stay in good shape for aid, while a student who drops from 12 credits to 9 after applying exam credits can lose part of a grant or scholarship tied to full-time enrollment. That is where the FAFSA question turns from simple to messy.
FAFSA, CLEP Credits, and Aid
FAFSA does not cover the CLEP exam fee, so you still pay the testing cost up front. The College Board charges $93 per CLEP exam, and many test centers add a small fee, so check both costs before you register. Use that number to compare the exam price with the tuition you would avoid by earning 3 or 6 credits.
The bigger issue sits after the score posts. CLEP credits can count toward your degree, and that can change how your school reads your enrollment and progress for aid. A 50 on a CLEP exam can replace a 15-week class, but your school may still ask whether you remain at 12 credits, 6 credits, or another aid line.
The catch: FAFSA looks at enrollment and need, not the exam itself. That means a student who earns 6 credits through CLEP may keep the same federal aid package if they still enroll full time, but the same student can lose part of a school grant if the new credit total drops below the school's cutoff.
A community-college transfer student who plans to test before the fall registration deadline should ask one blunt question: will these 3 or 6 credits count before aid disbursement? If the answer is yes, the school may recalculate the package before classes start; if the answer is no, the credits may help later in the term but not fix the first award notice. That timing matters more than most students expect.
When CLEP Credits Change Full-Time Status
Full-time status usually starts at 12 credits in a semester, and that number drives a lot of aid rules. If CLEP credits help you reach degree progress faster, your school may still use your registered credits, not just your earned credits, to decide whether you count as full time. That distinction matters for Pell Grants, institutional scholarships, and some state awards.
What this means: A homeschool senior who takes 3 CLEPs in one summer can enter college with 9 credits or 12 credits already done. That can move the student past a prerequisite, but it can also change how the school packages aid if it counts prior credits toward standing or degree level. Ask the registrar whether those credits post before census date, because census timing often drives aid math.
A school like Arizona State University or Miami Dade College may handle transfer and exam credit inside its own rules, not FAFSA's rules. That means one office can say the credits count and another can say the aid package stays the same only if the student keeps 12 enrolled credits. You need both answers, and you need them in writing.
A lot of students think more credits always helps. Not always. If a CLEP credit pushes you out of developmental math or English and into college-level work, you can save a semester; if it knocks you below a school's full-time line, you can lose a piece of grant money. That tradeoff deserves a hard look, not a guess.
What FAFSA Awards Can Shift
When CLEP credits change your degree progress, your aid office may recalculate the package before the next disbursement. That can happen after a score posts, after a transcript update, or after the census date your school uses for enrollment checks. A 12-credit schedule and a 9-credit schedule often trigger different award math, so compare both before you test.
- Pell Grants can shrink if your enrolled credits drop below full time. Check the 12-credit line before you stack CLEP on top of a light schedule.
- State grants often tie to credit load or degree status. Ask whether 6, 9, or 12 credits changes the award in your state.
- Institutional scholarships can have their own floor, like 15 credits or a 2.5 GPA. Read the scholarship terms, not just the FAFSA notice.
- Work-study depends on school budget and need. If your aid package shifts, your work-study hours can change even when your FAFSA stays filed.
- Federal loans usually track enrollment and cost of attendance. If you take fewer classes because CLEP moved you ahead, borrow only what you still need.
CLEP prep bundle can help if you want the exam side handled before you worry about aid math. I like that order better than the reverse, because the test plan should come first and the loan plan second.
The Complete Resource for FAFSA And CLEP
TransferCredit.org has a full resource page built for fafsa and clep — covering CLEP/DSST prep with chapter quizzes and video lessons, plus the ACE/NCCRS-approved backup course if you do not pass the exam. $29/month covers both, and credits transfer to partner colleges.
See CLEP Bundle Prep →A Real Student’s CLEP Aid Scenario
Picture a student at a four-year school who earns 12 CLEP credits from College Composition and Introductory Psychology before the fall term starts. Those 12 credits can wipe out two 3-credit classes and save one full semester of tuition, but they can also trigger a new aid review if the school counts them toward academic standing. Ask about that before the score posts, not after the refund hits.
If the student still enrolls in 12 credits for the fall, many awards stay steady. If the student drops to 9 enrolled credits because the CLEP credits replaced two classes, some grants and scholarships can shrink. That 3-credit gap matters, so the student should ask whether the aid office counts earned credits, enrolled credits, or both when it checks the package.
A student at the University of Texas at Arlington or a nearby community college can get different answers from different offices, and that is normal. The registrar may say the credits post in 48 hours, while financial aid may update only after the census date. Get both dates in writing and keep the email thread.
CLEP credits help most when the student plans the schedule first and the test second. That sounds backwards, but it saves money and avoids a nasty surprise on the award letter.
Before You Test, Check These Rules
Before one CLEP score changes a whole semester, check the school rules that control aid. A 12-credit line can protect a grant, but a 9-credit schedule can shrink it fast.
- Ask whether the school accepts CLEP credits for your major and degree plan. Some schools accept them for 30 or 60 credits, while others cap them lower.
- Check the minimum enrollment for aid. Many awards start at 12 credits for full time, but some institutional scholarships want 15 credits.
- Confirm satisfactory academic progress rules. A 2.0 GPA and a pace rule can matter as much as credit count.
- Ask how many transfer or exam credits the school allows. One school may post 3 credits fast, while another waits for an official transcript.
- Find out whether exam fees get reimbursed. If the school refunds $93 or offers a voucher, get the process in writing.
- Ask whether work-study or loans change after a CLEP score posts. A shift from 12 to 9 credits can change both the award and the repayment plan.
How to Protect FAFSA Eligibility
A smart CLEP plan starts with the aid office, not the testing calendar. The wrong order can cost you a grant check or a work-study slot, and that can happen after just one 3-credit change.
- Call the registrar and financial aid office before you register for the exam. Ask how CLEP credits post and whether they count before census date.
- Check your current credit load and compare it to the school's full-time line. If you sit at 12 credits, protect that number before you replace a class.
- Look at Pell, state grants, and scholarships one by one. A 2.5 GPA rule or 15-credit rule can change the award even if FAFSA stays active.
- Save every email, screenshot, and policy page. If the office gives you a 48-hour or 2-week timeline, write it down and follow up on that date.
- Adjust your class schedule only after you know the result. If the CLEP score moves you ahead, add a course or keep a buffer so you do not fall below the aid line.
How TransferCredit.org Fits
Frequently Asked Questions about FAFSA And CLEP
Start by checking your school’s Satisfactory Academic Progress rules and your aid office’s credit-count policy. CLEP credits can count toward degree progress at many schools, but FAFSA only pays for classes in an eligible program at an approved school, so 12 credits, 15 credits, and full-time status can all get treated differently.
No, FAFSA does not directly pay CLEP exam fees. FAFSA-based aid usually goes toward tuition, fees, room, and board at your school, while CLEP costs come from The College Board and the test center, so you pay those separately unless your school offers a refund, voucher, or fee help.
Most students assume CLEP just makes aid easier, but what actually works is checking how the credits affect enrollment level before you test. If CLEP drops you below 12 credits, your Pell Grant, loans, or work-study package can change fast, even if the credits still help you graduate sooner.
This applies to you if your school uses credit hours to set full-time status, aid amounts, or SAP rules. It doesn’t apply the same way if you’re in a program with flat-rate tuition, clock hours, or a nontraditional aid setup, because 6 credits, 9 credits, and 12 credits can trigger different rules.
What surprises most students is that passing a CLEP exam can help you finish faster without increasing aid, and sometimes it can lower the number of aid-eligible credits you take that term. A 50 on a CLEP earns the same college credit as an 80, so don’t overstudy for extra points you don’t need.
If you get this wrong, your school can cut your grant, loan, or work-study award after a credit review. That can leave you with a smaller refund, a balance due, or a part-time aid package if your 12-credit load drops to 9 or 6 after CLEP credits post.
A $0 change is possible, or your award can change by one full enrollment tier. If CLEP pushes you from 12 credits to 9, tell your aid office right away, because Pell Grant and loan amounts often tie to full-time, three-quarter-time, and half-time status.
The most common wrong assumption is that CLEP credits always help financial aid. They help your degree plan, but they can also change your cost of attendance, your enrollment status, and your need-based aid if your school counts them before or after the term starts.
Call your financial aid office and ask two things: whether CLEP counts toward SAP and whether it changes your full-time status for the term. Ask before the 100% refund deadline if your school has one, because a 12-credit schedule can look very different after scores post.
Yes, FAFSA CLEP credits can affect both loans and work-study if they change the number of credits you’re taking. Federal Direct Loans and work-study awards often depend on enrollment level, so a shift from 12 credits to 9 can change how much you can borrow or earn.
Most students try to stack CLEP on top of a 12-credit schedule, but what actually works is checking the aid cutoff before the exam. If one CLEP knocks out a 3-credit class, you may need another class or your aid office may treat you as less than full-time.
This matters for you if you use Pell Grants, federal loans, or work-study and your school ties aid to credit hours. It usually doesn’t matter as much if you’re paying cash and your school lets CLEP speed up graduation without changing your 12-credit or 15-credit status.
What surprises most students is that work-study depends on your aid package and enrollment status, not just on how many hours you want to work. If CLEP cuts your registered credits below your school’s full-time line, your work-study offer can shrink or disappear before the semester ends.
Final Thoughts on FAFSA And CLEP
FAFSA does not pay for CLEP exams, but CLEP credits can still change the size and shape of your aid package. That matters most when your school uses 12 credits for full time, 15 credits for some scholarships, or a census date that locks the term early. The cleanest move is boring, and that is fine. Check the registrar, the aid office, and the policy page before you test. A 3-credit exam can save a semester, but it can also cut a grant if you stop at 9 enrolled credits and never ask how the school reads your file. Do not guess on work-study or loans. Ask how your award changes if you replace one class, two classes, or a whole 12-credit block with exam credits. Then save the answers in writing and build your schedule around them. If you want the safest path, treat CLEP like a credit plan, not just a test plan. Confirm the rules, take the exam, and keep your enrollment where your aid needs it to stay.
How CLEP credits actually work
Ready to Earn College Credit?
CLEP & DSST prep + ACE/NCCRS backup courses · Self-paced · $29/month covers everything